


Oxley Holdings Limited has a good execution track record of monetising projects to pay down debt.
Residential property prices are high and this could translate to higher margins for the developer.
The group has taken pro-active steps to improve liquidity and has good access to bank loans and capital market funding.
We think that the 2023 bonds are the most attractive along the OHLSP curve.
Property buyers are willing to pay more for homes amidst the pandemic and developers may report good margins from the strong demand for residential properties. One such developer is Oxley Holdings.
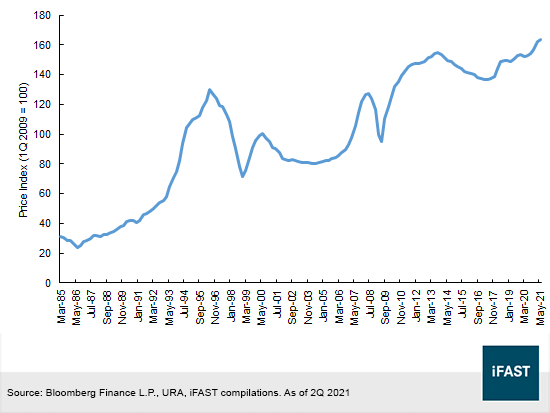
According to the Urban Redevelopment Authority (“URA”) of Singapore, housing prices are at their record highs. The URA private residential property index for all residential properties increased 0.9% during the second quarter of 2021 (“2Q 2021”) and is now in unchartered territory (Figure 1).
Figure 1: The URA all residential property price index
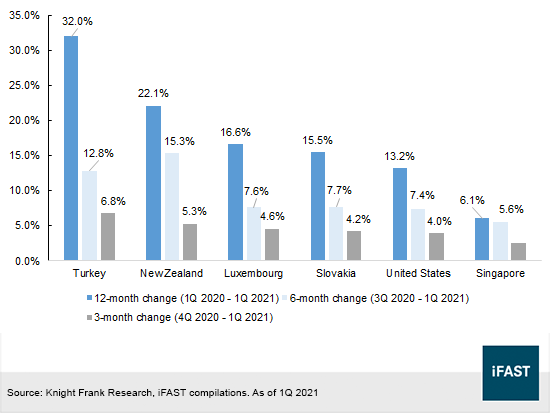
The phenomenon of pandemic housing bubbles is not restricted to Singapore alone as countries such as Turkey, New Zealand and Luxembourg have seen prices rising as high as 32% over the past year. According to Knight Frank, housing prices in Turkey surged 32% between 1Q 2020 and 1Q 2021 while prices in New Zealand and Luxembourg increased by 22.1% and 16.6% respectively (Figure 2).
Figure 2: Change in property prices by country
Set against the backdrop of high property prices, Oxley Holdings Limited (“Oxley”) recorded a 58% YoY gain in revenue during the second half ended 30 June 2021 (“2HFY2021”). Group revenue increased mainly due to higher contributions from projects in Cambodia, Singapore and Ireland. In tandem with the top-line gains, the amount of secured sales increased by 12.4% from SGD 8.57b on 31 August 2020 to SGD 9.63b on 8 August 2021.
The rate of secured sales has slowed down in recent months but Oxley may increase future revenue by selling another SGD 478m of properties in Singapore and SGD 1,966m of properties located overseas. These include the Gaobeidian project in China and the Oxley Towers Kuala Lumpur project in Malaysia, both of which have the highest remaining gross development values of SGD 1,075m and SGD 674m respectively (Table 1). In addition, the developer has a few other projects in the pipeline with a total potential gross development value of SGD 2.05b.
Table 1: Oxley's Singapore and overseas development projects
|
Project |
TOP |
Effective stake (%) |
Future progress billings (effective stake, in SGD m) |
Remaining GDV (effective stake, in SGD m) |
|
1953 |
2Q22 |
100% |
48 |
46 |
|
Affinity at Serangoon |
4Q22 |
40% |
326 |
58 |
|
INSPACE |
2Q22 |
49% |
15 |
45 |
|
Kent Ridge Hill Residences |
3Q22 |
100% |
467 |
157 |
|
Mayfair Gardens |
2Q-3Q 2022 |
100% |
200 |
46 |
|
Mayfair Modern |
2Q-3Q 2022 |
100% |
137 |
78 |
|
Parkwood Residences |
2Q23 |
100% |
2 |
27 |
|
Riverfront Residences |
4Q22 |
35% |
325 |
21 |
|
Sea Pavilion Residences |
TOP-ed |
100% |
13 |
- |
|
Sixteen35 Residences |
TOP-ed |
100% |
8 |
- |
|
The Addition |
TOP-ed |
100% |
2 |
- |
|
The Verandah |
TOP-ed |
100% |
113 |
- |
|
Royal Wharf |
2018-2020 |
100% |
- |
6 |
|
Dublin Landings* |
2019-2021 |
84% / 79.5% |
32 |
9 |
|
The Bridge |
2018 |
50% |
1 |
21 |
|
The Palms |
2021 |
79% |
18 |
70 |
|
The Peak |
2020-2022 |
79% |
73 |
74 |
|
Oxley Towers Kuala Lumpur |
2023 |
100% |
130 |
674 |
|
Mozac |
2024 |
36% |
- |
37 |
|
Gaobeidian |
TBA |
27.50% |
25 |
1,075 |
| Source: Company, iFAST compilations. As of 8 August 2021. Progress billings as of 30 June 2021. Note: *Figures for Dublin Landings include commercial and residential units. | ||||
Oxley may use future progress billings to pay down financial obligations. Barring any construction delays, approximately ~SGD 1.78b of progress billings may be collected from property buyers.
Referring to Table 1, the following projects are expected to obtain their TOP by the end of 2022 and the project cash flow should help the group in paying down debt. Such projects include 1953, Affinity at Serangoon, INSPACE, Kent Ridge Hill Residences, Mayfair Gardens, Mayfair Modern, Riverfront Residences, The Verandah and the Peak. With regard to the Peak in Cambodia, the development is already 87% sold and has SGD 130m of future progress billings.
Figure 3: Debt maturity profile
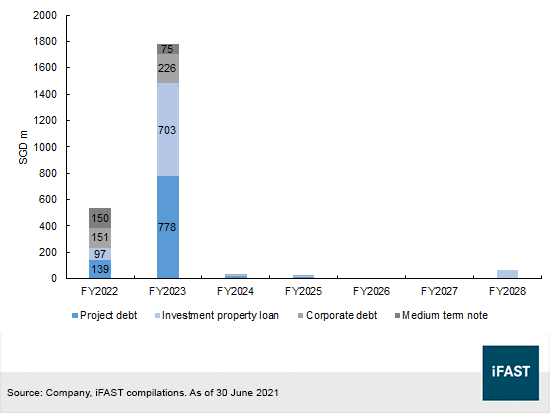
Oxley has a weak liquidity profile even though group borrowings dropped from SGD 3.03b in FY2020 to SGD 2.51b in FY2021. Total cash and cash equivalents added to SGD 215.8m in June, and that is insufficient to cover its SGD 772.8m of current financial liabilities.
However, to meet its current financial obligations, Oxley may (i) drawdown on its cash position (SGD 215.8m), (ii) sell its land (SGD 100m), (iii) use the proceeds from its recently issued medium term note (SGD 70m), (iv) pay down the project debt using project cashflows (SGD 139m), (v) refinance its investment property loan (SGD 97m) and (vi) pay off the remaining SGD 150m of corporate debt using proceeds from the completion of overseas development projects.
We believe that Oxley will have continued access to diversified funding sources including banks and debt capital markets. The company guided that it will maintain a cash balance of between 5% and 10% of revenue for working capital requirements. In addition, it will keep as much unencumbered assets for financial flexibility.
Group gearing has declined but financial leverage is high compared to most other developers. The proportion of net debt to equity remains at an elevated level of ~218.4% as at 2HFY2021 (2HFY2020: ~247.9%), and it has a debt to total asset ratio of ~60.2%. As a reference, Heeton Holdings Limited has a net debt to equity ratio of ~103.7%, and debt to total asset ratio of ~47.2%.
Relative valuation
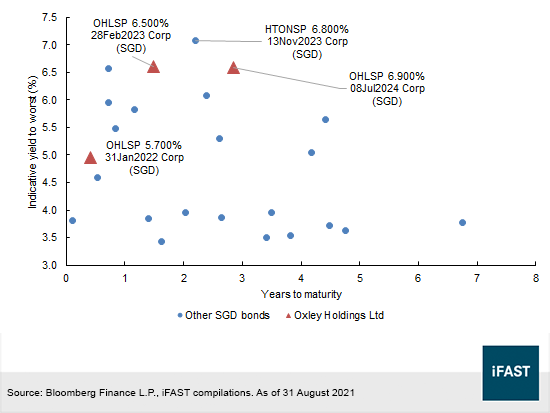
In view of its access to bank funding, improved gearing and high property prices, we are overweight the OHLSP curve. The medium term notes are issued by Oxley MTN Pte. Ltd. and guaranteed by Oxley Holdings Limited. Investors may consider the OHLSP 6.500% 28Feb2023 Corp (SGD) at its indicative yield to worst of 6.61% on 31 August 2021. The OHLSP 6.5% 2023’s currently offer the best value as it has the highest yield and shortest maturity. However, investors should keep in mind that the 2023 and 2024 bonds have small issue sizes, and it may be difficult to sell them at a favourable price in future.
On a separate note, if there is available liquidity, high-yield investors may also look at the HTONSP 6.800% 13Nov2023 Corp (SGD) at its indicative yield to worst of 7.08%. The sinkable bonds have a defined amortisation schedule and maturity date in November 2023.
Heeton announced results for the half-year period on 6 August 2021 (“1H21”). Total revenue increased 38.4% from SGD 12.6m in 1H20 to SGD 17.5m in 1H21. The company turned profitable as it reported a profit after tax of SGD 510,000, up from a net loss of SGD 8.93m in 1H20. Net operating cash flows stayed negative around –SGD 3.89m but there is adequate liquidity – made up of SGD 76.86m of cash and SGD 11.2m of fixed deposits to cover short-term borrowings.
Figure 4: Relative valuation of comparable SGD bonds
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in OHLSP 6.900% 08Jul2024 Corp (SGD). The analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!


